FHA multifamily financing lets you purchase a property with more than one unit to help you start your journey as a real estate investor. The application process comes with flexible credit qualifications and a low down payment, but you’ll also have to meet owner occupancy requirements and make sure the property meets the FHA’s standards.
Find out all the requirements you’ll need to apply for an FHA multifamily loan, plus how much you can spend and what other financing options may be worth exploring.
- FHA loans can be used for multifamily properties with up to four units.
- You must live in one of the units as your primary residence in order to qualify.
- Projected rental income may be used as part of your qualifying income for the loan.
- FHA loan limits depend on the number of units in the property.
What Are the Requirements for An FHA Multifamily Home Loan?
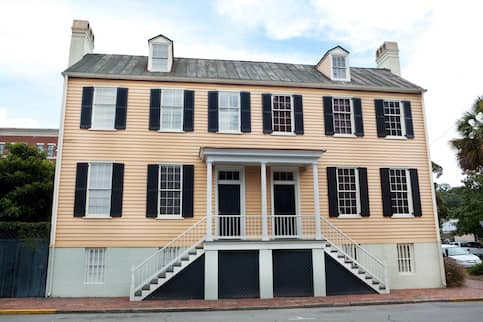
It is possible to buy a multifamily home using a traditional FHA loan, as long as you and the property both qualify. Properties with up to four units are eligible, as long as you live in one of the units as your primary residence. In other words, you can use an FHA loan to purchase a duplex, triplex or quadplex.
Compare Mortgage Offers From Verified Lenders:
FHA Multifamily Loan Requirements
Buying a multifamily home with an FHA loan comes with a distinct set of guidelines.
Owner Occupancy
In order to use an FHA loan for a multifamily property, one of the units must be used as your primary residence. That means you must live in it for the majority of the year for at least one year, but you can rent out the other units to help offset your mortgage costs. After a year, you may move and rent out all the units while keeping the FHA loan. One factor to consider if you move: In most cases, you can only have one FHA loan at a time. If you want to finance a different home for yourself, you likely need to explore other loan types.
Maximum Loan Limits
The maximum amount you can borrow with an FHA loan depends on your location and the number of units in the property. These are the latest limits for 2026.
| Number of units | Loan limit in most areas | Loan limit in high-cost areas | Loan limit in Alaska, Hawaii, Guam and the U.S. Virgin Islands |
|---|---|---|---|
| 1 | $541,287 | $1,249,125 | $1,873,625 |
| 2 | $693,050 | $1,599,375 | $2,399,050 |
| 3 | $837,700 | $1,933,200 | $2,899,800 |
| 4 | $1,041,125 | $2,402,625 | $3,603,925 |
Down Payment And Up-Front Mortgage Insurance Premium
Purchasing a multifamily home with an FHA loan comes with some up-front costs. Just like any other FHA loan, you must make a down payment of at least 3.5%. But that can jump to 10% depending on your credit score.
While these lower down payment requirements sound attractive, it can be difficult to find a multifamily property within the loan limits in many parts of the country. Making a larger down payment could allow you to explore more properties while staying within the FHA guidelines.
The other cost to consider is the FHA up-front mortgage insurance premium (MIP). It’s 1.75% of your loan amount and is either due as cash at closing or rolled into your mortgage payments. Just remember that rolling it into your loan will result in higher mortgage payments and more interest paid over time.
Debt-To-Income Ratio
Your debt-to-income ratio (DTI) compares how much of your gross monthly income goes to paying down debt. There are two types of DTIs lenders consider:
- Front-end DTI: This just includes your housing expenses, which should stay under 40%.
- Back-end DTI: This includes all of your monthly debt payments and should be no more than 50%.
If your DTI is too high, you can either focus on paying down debt or adding more income sources.
Income
In order to qualify for FHA multifamily financing, you must have steady income. Lenders usually verify this information through paystubs, W-2s, tax returns and bank statements. In some instances, lenders might allow you to claim a portion of the anticipated rental earnings as part of your income, but you may need to have signed leases to get this approved.
Credit Score
Your credit score impacts both your eligibility and your down payment amount. In order to qualify for a 3.5% down payment, you’ll typically need a 580 credit score. While some lenders may accept a credit score between 500 and 579, in those cases you’ll usually need to make a 10% down payment for your FHA loan.
There are also specific waiting periods for certain items that may be on your credit report. If there’s a foreclosure, the minimum waiting period is 3 years from the date of the foreclosure sale. For Chapter 7 bankruptcy , the waiting period is 2 years from discharge at minimum. In some extenuating circumstances, those waiting periods can be shortened to 12 months (if your new mortgage is manually underwritten and you meet certain financial criteria). The waiting period is 12 months if you’ve had a Chapter 13 bankruptcy (you also must show consistent on-time payments and have permission in writing from the court).
Appraisal
Your FHA multifamily property must also get an appraisal, which does two things: confirms that the purchase price doesn’t exceed the appraised value and also ensures the property is safe and structurally sound. The appraiser will look for utility meters for each unit, examine the structure, roof, handrails and more. This is slightly stricter than conventional loan requirements, which focus on major deficiencies that make the property unlivable, such as roof leaks, missing components or a damaged foundation.
Cash Reserves
If you’re purchasing a three- to four-unit property with an FHA loan, you’ll need a minimum of 3 months of mortgage payments (including principal, interest, taxes and insurance). These funds cannot come from a gift.
What’s Your Goal?

Buy A Home
Discover mortgage options that fit your unique financial needs.
Refinance
Refinance your mortgage to have more money for what matters.

Tap Into Equity
Use your home’s equity and unlock cash to achieve your goals.
Pros And Cons Of FHA Multifamily Financing
There are both advantages and disadvantages to using an FHA loan for a multifamily property.
| Pros | Cons |
|---|---|
| Credit flexibility: FHA loans come with lower minimum credit scores. | Up-front and annual mortgage insurance premium: The annual fee is charged for the life of the loan if your down payment is less than 10%; otherwise it stays on for 11 years. |
| Low down payment minimum: You can purchase a multifamily home with just 3.5% down, compared to 5% with a conventional loan. | Appraisal: The structure and soundness standards are higher than for other loan types. |
| Rental income on application: You may be able to use the projected income from rental units as part of your qualifying income. Contact your local Homeownership Center to get help. | Owner occupancy: You must live in one of the units as your primary residence for at least a year. |
Ready To Become A Homeowner?
Get matched with a lender that can help you find the right mortgage.
Alternative Multifamily Financing Options
What other types of loans can you use for a multifamily property instead of an FHA loan?
- Conventional mortgage: Conventional loans have become more accessible in recent years. Instead of a 15% to 25% down payment requirement on two- to four-unit investment properties, you can now qualify for a conventional multifamily loan with just a 5% down payment in most areas of the country, as long as you live in one of the units. You may need to pay more if you live in a high-cost area.
- Commercial mortgage: A commercial mortgage lets you buy a multifamily property without having to live in it. But the eligibility requirements are more stringent than an FHA loan, and you’ll likely need a larger down payment – around 25%.
Take The First Step To Buying A Home
Find a lender that will work with your unique financial situation.
FAQ
The Bottom Line: It’s Possible to Climb The Real Estate Ladder With FHA Multifamily Financing
If you’re interested in purchasing a multifamily property as an investment, you don’t have to wait until you can afford a commercial mortgage with a huge down payment. Instead, you can take advantage of FHA loan financing to purchase a building and live in one unit while earning rental income from the rest.
Ready to start running some numbers? Check out today’s latest FHA loan rates.


Ben Shapiro
Ben Shapiro is an award-winning financial analyst with nearly a decade of experience working in corporate finance in big banks, small-to-medium-size businesses, and mortgage finance. His expertise includes strategic application of macroeconomic analysis, financial data analysis, financial forecasting and strategic scenario planning. For the past four years, he has focused on the mortgage industry, applying economics to forecasting and strategic decision-making at Quicken Loans. Ben earned a bachelor’s degree in business with a minor in economics from California State University, Northridge, graduating cum laude and with honors. He also served as an officer in an allied military for five years, responsible for the welfare of 300 soldiers and eight direct reports before age 25.