
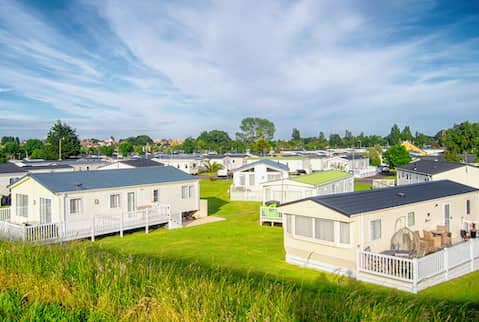
A manufactured home can offer an affordable path to homeownership, but buying one comes with its own set of rules. From choosing the right home loan to deciding whether to lease or buy the land beneath the home, there are several important issues to consider along the way.
Can you get a loan on a manufactured home? Yes – but a lot of factors can affect your financing options. Here’s what you need to know.
- Loan options for manufactured homes include conventional, Federal Housing Administration (FHA), Department of Veterans Affairs (VA), U.S. Department of Agriculture (USDA) and chattel loans.
- Manufactured, mobile and modular homes are all built in a factory, but the similarities stop there when it comes to construction codes and financing options.
- Manufactured homes must have a certification label confirming it was built on or after June 15, 1976.
- Financing for manufactured homes depends on whether you own the land or rent the land underneath it.
What Is A Manufactured Home?
A manufactured home is a house that is built in a factory and attached to a steel chassis before being transported to the buyer’s site. A home qualifies as manufactured if it meets the Department of Housing and Urban Development (HUD) federal safety guidelines and carries a certification label confirming it was built on or after June 15, 1976.
Financing a manufactured home works differently from getting a standard mortgage because of the way the home is set up. The options for a manufactured home loan depend on two key factors: the home itself and whether you own or lease the land it sits on.
Compare Mortgage Offers From Verified Lenders:
How Manufactured Homes Differ From Modular And Mobile Homes
These three terms are often used interchangeably outside the real estate industry, but there are clear distinctions.
- A manufactured home is built to HUD safety and construction standards and must be certified. It can be permanently affixed to land that you own or placed on leased land. A single-wide home is comprised of one long unit, while a multisection home has more than one unit, and those sections are joined after being transported to your land.
- A mobile home refers to a factory-made structure that was built before June 15, 1976, and is generally ineligible for mortgage financing.
- A modular home is factory-built but then assembled on a permanent foundation. It must follow local building codes. You can use a standard mortgage to buy one.
The specific classification of your home determines which loan programs are available to you, so it’s important to confirm the home’s build date and HUD status before you apply for a loan.
What’s Your Goal?

Buy A Home
Discover mortgage options that fit your unique financial needs.
Refinance
Refinance your mortgage to have more money for what matters.

Tap Into Equity
Use your home’s equity and unlock cash to achieve your goals.
Manufactured Home Financing Options
Here’s how you can get a loan on a manufactured home.
Conventional Loans
A conforming conventional loan must meet the standards set by Fannie Mae or Freddie Mac. For example, Fannie Mae requires that the home be at least 400 square feet, at least 12 feet wide, on a permanent foundation and have a Real Property title qualify.
You could qualify for a conventional loan with as little as 3% down. Your approval is based on an overall assessment of credit risk; while individual lenders may set their own minimums, Fannie Mae and Freddie Mac have not required a specific minimum credit score since November 2025.
FHA Loans
A Federal Housing Administration loan is a government-backed mortgage that you can use to buy a manufactured home, even if you have a less-than-ideal credit score and limited savings for a down payment.
There are two types of FHA loans available for financing manufactured homes.
Title I FHA Loans
Title I allows you to finance a manufactured home even if you don’t own the land, but you must have a signed lease of at least 3 years for the property where the home will sit, and the home must be your primary residence. These loans work well if you want to buy a manufactured home in a planned community.
You can use a Title I loan in a variety of ways: to purchase just the home, buy land or refinance an existing manufactured home loan. Title I can also work for a combination purchase of the home and land or lot together.
The amounts you can borrow in 2026 are:
| Type Of Manufactured Home/Land/Lot | Maximum Loan Available |
|---|---|
| Single-wide home | $105,532 |
| Single-wide home with lot/land | $148,909 |
| Multisection home | $193,719 |
| Multisection home with lot/land | $237,096 |
Title II FHA Loans
This kind of FHA loan can only be used if the manufactured home you purchase is permanently affixed to the land that you own or plan to buy. Other requirements for the home include:
- Must have been constructed on or after June 15, 1976
- Must be a primary residence (same as Title I loans)
- Must have a minimum floor plan of 400 square feet
- Cannot be located on leased land
Title II loans have higher borrowing limits, based on the FHA’s area limits. For 2026, the limits range from $541,287 for low-cost areas and up to $1,249,125 for high-cost areas.
FHA Title loans generally require a minimum credit score of 500, with a 10% down payment for scores below 580, and 3.5% down for scores of 580 or higher, depending on the lender and financial profile.
VA Loans
The Department of Veterans Affairs guarantees VA loans for eligible veterans, active-duty service members and qualifying surviving spouses. You can use a VA loan to buy a manufactured home to place on land you own or to buy both the home and the land together. You can also use it to refinance a manufactured home that you already own.
Borrowers pay a one-time VA funding fee, which varies by loan type, down payment, and whether it’s the borrower’s first time using a VA loan. For manufactured homes not permanently affixed to a foundation, the VA charges a flat 1% funding fee. Manufactured homes on a permanent foundation follow the standard VA purchase loan rate chart, which ranges from 1.25% to 3.3%, with some exceptions.
Other VA requirements for financing a manufactured home include:
- The manufactured home must be at least 400 square feet for single-wide and 700 for multisection.
- It must be permanently affixed to a foundation.
- It must be titled as real estate and compliant with local zoning requirements.
- The home cannot sit on leased land.
- Must be the borrower’s primary residence.
Chattel Loans
A chattel loan can be used to finance a manufactured home as personal property rather than real estate. It’s typically used when the home sits on leased land.
Unlike a traditional mortgage, a chattel loan can also be used to finance other movable property, such as an RV. Chattel loans are generally easier to obtain and close more quickly than traditional mortgages, but they may carry higher interest rates, shorter terms and fewer consumer protections.
USDA Loans
A USDA guaranteed home loan program is a government-backed mortgage (no down payment needed) offered through the U.S. Department of Agriculture’s Rural Development program. These loans come with very specific requirements. You have to purchase in a USDA-eligible rural area, meet the area’s income requirements (your household income cannot exceed 115% of the area’s median income), and live in the home as your primary residence. If you can meet these criteria, a USDA loan can be one of the most affordable financing options available.
While the USDA does not specify a credit score, many lenders require at least a 640.
To qualify, the home must be titled as real property versus personal property and built on a permanent foundation, located on land you own or are purchasing. Additional housing requirements for USDA financing include:
- The home must be transported directly from the manufacturer to the site.
- Must have a floor plan of no less than 400 square feet.
- Must be the borrower’s primary residence.
- Must be installed on a permanent foundation that was built according to FHA guidelines.
- Must meet the Federal Manufactured Home Construction and Safety Standard.
Manufactured Home Loan Options: At A Glance
Use the comparison table below to get an idea of which loan could be right for you.
| Type of Loan | Min. Credit Score | Min. Down Payment | Lease or Own Land | May Be Best For |
|---|---|---|---|---|
| Conventional | No set minimum | 3% | Must own the land | Buyers who own land and have good credit |
| FHA Title I | 500 (580) | 10% (3.5%) | Lease or own | Buyers with leased land and lower credit scores |
| FHA Title II | 500 (580)* | 10% (3.5%) | Must own or buy land with the loan (no lease allowed) | Buyers who want to purchase land and a home, or want to purchase land for a home they already own |
| VA Loan | No set minimum | 0%. For manufactured homes, some lenders may still ask for up to 5%. | Must buy or own land (no lease allowed) | For eligible service members and veterans |
| Chattel Loan | Varies by lender | 5% to 20% | Lease or own | Buyers on leased land |
| USDA Loan | USDA does not list one; lenders typically like to see at least 640 | No down payment required. | Must buy or own land (no lease allowed) | Great for low-income or middle-income buyers in rural areas |
Ready To Become A Homeowner?
Get matched with a lender that can help you find the right mortgage.
Eligibility Requirements For Manufactured Home Loans
Credit Score
The credit score you’ll need will depend on the loan and lender. Regardless of which loan you choose, a higher score will generally get you better rates and terms.
Down Payment
Down payment requirements vary by loan type. You’ll also pay closing costs on the mortgage, so expect to pay an additional 3% – 6% of the loan amount.
Land Ownership
Whether you own or lease the land will be one of the biggest factors in determining your manufactured home loan options. Owning or buying the land allows you to consider conventional, FHA Title II and VA financing. Leasing the land, on the other hand, limits you mainly to FHA Title I and chattel loans.
Property Standards
Manufactured homes must meet the size and construction standards of your loan type. All major programs require HUD Code construction timeline (on or after June 15, 1976), a HUD certification label and that the house be affixed to a permanent foundation with real-property classification.
- Conventional: The house must be at least 12 feet wide and have a gross living area of at least 400 square feet.
- FHA Title II: The house must have at least 400 square feet of floor area, be on a permanent foundation that meets HUD’s Permanent Foundations Guide for Manufactured Housing (PFGMH), and be certified by a licensed engineer.
- FHA Title I: At least 400 square feet of floor area; at least 8 feet wide and 40 feet long in traveling mode (the HUD definition of a manufactured home).
- VA loan: The house must be at least 400 square feet for single-wides (minimum 10 feet wide) and 700 square feet for double-wides (minimum 20 feet wide), and must be on a permanent foundation.
- USDA (Section 502 Guaranteed): Similar to a VA loan, the house must be 400 square feet, but for a USDA loan, if it’s a single-wide built home, it must be 12 feet wide. Double-wide homes must be at least 20 feet wide, be new units and be located in a USDA-eligible rural area.
Take The First Step To Buying A Home
Find a lender that will work with your unique financial situation.
What To Consider Before Financing A Manufactured Home
Think About The Kind Of Home You Can Afford To Buy
Many custom-built manufactured homes come with significant upgrades and custom finishes that can be expensive. Decide how much space you need (often the larger the floorplan, the bigger the price tag) and what you can comfortably afford. If you’re buying in a planned community, remember to factor in monthly homeowners association (HOA) fees and utility hook-up costs.
Consider If You Will Lease Or Own The Land
If you are not sure whether to rent or buy land for your new home, consider the long-term costs of both options. If you lease the land or rent a lot in a manufactured community, you’ll have to deal with ongoing rental costs and fees. Buying land may seem more expensive at first, but you’ll have more choices for financing, and you’ll build equity over time.
Compare Your Loan Options
Research lenders and loan types to compare what’s available for your financial profile and needs, from interest rates to origination fees.
Apply For A Manufactured Home Loan
Gather your financial documents before you apply: You’ll need to provide pay stubs, W-2 forms, recent bank statements and usually 2 years of tax returns. When financing a manufactured home, you may also need, where applicable:
- The HUD certification label number for the home
- Affidavit of fixture for the home
- The title of the home and whether it’s titled as personal property (not attached to the land) or real property (attached)
- If you are leasing land or renting a lot, a copy of the lease agreement
- If you own land or plan to buy land, all the documents connected to its purchase
FAQ
The Bottom Line: Learn Your Options Before You Buy A Manufactured Home
The right manufactured home financing for your situation will depend on factors such as whether you own or lease the land, your credit score, your down payment savings and the size and location of the home you want to buy.
Compare home loan options and lenders to find the best fit for your needs, and make sure to research the type of manufactured home you’d like to buy. After all, even though these homes are factory-built, they’re far from one size fits all.


Ben Shapiro
Ben Shapiro is an award-winning financial analyst with nearly a decade of experience working in corporate finance in big banks, small-to-medium-size businesses, and mortgage finance. His expertise includes strategic application of macroeconomic analysis, financial data analysis, financial forecasting and strategic scenario planning. For the past four years, he has focused on the mortgage industry, applying economics to forecasting and strategic decision-making at Quicken Loans. Ben earned a bachelor’s degree in business with a minor in economics from California State University, Northridge, graduating cum laude and with honors. He also served as an officer in an allied military for five years, responsible for the welfare of 300 soldiers and eight direct reports before age 25.