
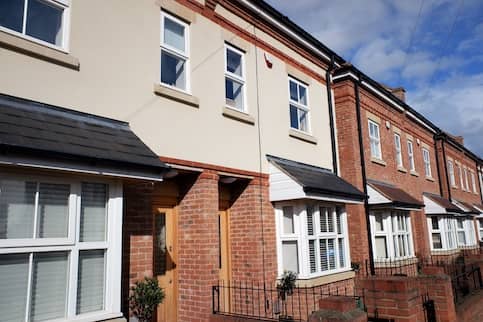
Loans insured by the Federal Housing Administration (FHA) are designed to help homebuyers purchase primary residences with flexible loan terms. However, if you’re interested in using an FHA loan for an investment property, there is a workaround: house hacking. In such a scenario, you would use an FHA loan to buy a multi-unit property, then live in one unit and rent out the others – and count the rental income to qualify for financing.
You have to meet certain qualifications, but done right, house hacking can help you dramatically reduce – or even fully cover – your monthly mortgage costs. Meanwhile, you get into a home with just 3.5% down and a lower credit score than many other loan programs allow.
Learn how FHA loans for multi-unit investment properties work and the specific rules you need to follow.
- FHA loans cannot be used purely to purchase an investment property, but you can buy a multi-unit property, live in one unit and rent out the others. This is known as house hacking.
- Qualified borrowers can buy up to a fourplex with just 3.5% down and use rental income from the other units to help qualify for FHA financing, subject to its 75% rental income rule.
- FHA has a self-sufficiency test for three- and four-unit properties requiring that the projected rental income cover the full mortgage payment; duplexes are excluded from this test.
Can You Use FHA Loans For Investment Property?
The short answer: No. FHA loans are meant to encourage homeownership of a primary residence. FHA’s occupancy requirement is nonnegotiable: At least one borrower must occupy the property as their principal residence within 60 days of closing and for at least a year. When you close on an FHA loan, you sign an affidavit agreeing to these terms.
The FHA allows owners to have only one primary residence at a time, with a few narrow exceptions to the occupancy rule. These include relocation, divorce or changes in family size. FHA-approved lenders can perform occupancy inspections on FHA-financed properties. Claiming you live in a property when you don’t is occupancy fraud – a federal offense that can result in immediate loan acceleration (meaning the loan is due in full), civil penalties and criminal charges.
How FHA Loans Work For Multi-Unit Properties
Though using FHA loans solely for investment properties isn’t allowed, the agency does allow you to purchase a residential property with up to four units, live in one unit and rent out the others. A bonus: You can count the rental income from the leased units to qualify for financing (more on how that works later). This is generally called house hacking.
For 2026, FHA loan limits increased, reflecting rising home values in most of the country.
| Units | FHA Floor Limit | FHA Ceiling Limit |
|---|---|---|
| 1 | $541,287 | $1,249,125 |
| 2 | $693,050 | $1,599,375 |
| 3 | $837,700 | $1,933,200 |
| 4 | $1,041,125 | $2,402,625 |
FHA considers anything more than four units a commercial property, making them ineligible for FHA financing. If you’re buying commercial property, you’ll have to consider commercial loans offered by conventional lenders.
What’s Your Goal?

Buy A Home
Discover mortgage options that fit your unique financial needs.
Refinance
Refinance your mortgage to have more money for what matters.

Tap Into Equity
Use your home’s equity and unlock cash to achieve your goals.
Using Rental Income To Qualify For An FHA Loan
The great thing about applying for FHA financing on a multi-unit property is that you can use rental income to qualify for the loan. Lenders can count rental income from other units as “effective income.” This is calculated as 75% of the gross market rent for the non-owner-occupied units, minus a vacancy factor.
For example, if you buy a duplex (two units), live in one of them and rent out the other for $1,800 per month, your lender will count $1,350 a month (75% of $1,800) toward your qualifying income. That additional income can meaningfully lower your debt-to-income (DTI) ratio and boost your buying power.
Additionally, the FHA allows borrowers to buy a single-family home with one accessory dwelling unit (ADU) – a living space on the property or attached to the home that’s separate from the primary living space – and to count the entire property as a single unit. Borrowers may use projected income from an ADU unit to help qualify for FHA financing, but that rental income can account for no more than 30% of their monthly effective income.
Ready To Become A Homeowner?
Get matched with a lender that can help you find the right mortgage.
FHA Self-Sufficiency Test: Why It Matters
A big hurdle for FHA loans on three- or four-unit multifamily properties is passing the self-sufficiency test. The rule states that the net rental income from the property must be enough to cover the full monthly PITI payment (principal, interest, taxes, homeowner’s insurance and FHA mortgage insurance).
It’s calculated by taking the fair market rent for all units (including the one you’re living in) and subtracting 25% of that value to cover vacancies and maintenance. This net rent amount must be equal to or greater than the PITI payment to qualify for an FHA loan for a three- or four-unit property.
Passing this test is particularly difficult in high-cost markets where rent estimates generally won’t support PITI payments after the rule is applied.
Self-sufficiency formula example:
- Total rent potential: $4,000/month
- Minus 25%: $1,000
- Net rental income: $3,000
- PITI payment must be $3,000 or less to qualify for an FHA loan
Options if you fail the test:
- Make a larger down payment to reduce the loan amount and the monthly PITI.
- Buy mortgage points, which are upfront fees, to lower your interest rate and payment.
- Buy a duplex, which skips the test entirely.
- Switch to conventional financing, which does not require a self-sufficiency test. However, investment properties typically require higher down payments, usually 15% – 30% of the purchase price.
Take The First Step To Buying A Home
Find a lender that will work with your unique financial situation.
FHA Rules For Non-Occupying Co-Borrowers
Sometimes a borrower needs another person on the loan to qualify on income or credit score. The FHA allows this with specific guardrails. A non-occupying co-borrower can be added to an FHA loan if the co-borrower is a family member (related by blood, marriage or law).
However, this doesn’t change the occupancy requirement. One borrower on the loan must still live in the property. The co-borrower’s income and financial profile can help qualify for the loan, but the co-borrower doesn’t have to live there.
After Year One: Conversion Strategy
This is where house hacking can pay off. After satisfying the FHA’s one-year occupancy rule, you can convert your FHA-financed property into a pure rental. If you move out and rent all units, your original mortgage terms won’t change. The property can then function as a fully rented, cash-flowing investment property.
But where will you live? You may be able to buy a second home with an FHA loan at that point, as long as you qualify for the earlier exceptions (relocation, divorce or changes in family size) or if you were a previous co-signer or co-borrower and want to get your own home with an FHA loan. There are strict limitations on carrying two active FHA loans at the same time, so consult an FHA-approved lender before assuming you can take out another FHA mortgage.
To be clear, buying a multi-unit property with the intention of never living there is fraud. Instead, plan to buy it and live there for at least a year before converting it entirely to a rental. Intent matters to lenders, as does documentation. Keep records of your occupancy in case your mortgage lender comes knocking with questions.
FHA Vs. Conventional Loans For Investment Properties
Here’s a side-by-side comparison of how FHA loans and conventional loans work for multi-unit investment properties.
| Requirement | FHA | Conventional |
|---|---|---|
| Minimum down payment | 3.5% (with score of 580+) | 15% for 1 unit; 25% for 2 – 4 units |
| Credit score minimum | 500 (with 10% down); 580 (with 3.5% down) | 640 – 700 (varies by LTV, DTI ratios) |
| Occupancy rules | Primary occupancy required in at least 1 unit | None; can be purchased solely for rental purposes |
| Mortgage insurance | Upfront MIP (1.75%) plus annual MIP (varies), usually for life of loan or 11 years with more than 10% down | PMI with less than 20% down; may be removed once you reach 20% equity |
| Self-sufficiency test | Required for 3 – 4 units but not for duplexes | Not required |
| Max units | 4 | 4 (residential); no limit (commercial) |
Considerations When Using FHA Loans For Rental Properties
House hacking with an FHA loan has advantages, but there are also risks to consider:
- Annual MIP lasts the life of the loan: If you put down 3.5%, you’re stuck with an FHA mortgage insurance premium (MIP) for the entire loan term (or 11 years with 10% or more down). If you convert it into a rental after year one, you’ll carry that cost until refinancing into a conventional loan, which requires 20% equity.
- Appraisal risk on three- and four-unit properties: If the self-sufficiency rent estimate from the FHA appraiser comes in too low, you may not qualify for FHA financing. Get comparable rental data before making an offer or, to avoid the self-sufficiency test altogether, buy a duplex (two units) instead.
- Lender overlays: Some lenders add extra requirements (such as a higher credit score or lower debt-to-income ratio) on FHA’s rules. Shop lenders, not just rates.
- Consider new landlord duties: Are you ready for the responsibility of managing difficult tenants, repairs, vacancy periods and other hurdles that come with being a landlord? Weigh the pros and cons of being a landlord before house hacking.
FAQ
The self-sufficiency test isn’t required for duplexes, so buying a two-unit property avoids this problem entirely.
Bottom Line: House Hacking Your Way To Passive Income
While FHA loans aren’t issued for properties purchased solely for investment purposes, house hacking is a savvy workaround. If you’re willing to live in one unit of a multi-unit property for at least a year, FHA financing gives you a solid entry point into real estate investing, with down payment and credit flexibility that most investment property conventional loan programs can’t match.
The math works best for duplexes so you avoid the self-sufficiency test and still collect rental income. Triplexes and fourplexes offer more income potential but usually cost more and require the property to essentially pay for itself on paper. Compare and rates today.


Deborah Kearns
Deborah Kearns is an award-winning independent journalist with more than 15 years of experience covering real estate, mortgages and personal finance. Her work has appeared in the Wall Street Journal, Kiplinger, U.S. News & World Report, Quartz, CNN, Forbes, Fortune, Newsweek, The Associated Press and dozens of other outlets. She previously led content and communications at a Top 15 national mortgage company and held writing and editing roles at Bankrate, NerdWallet, LendingTree and RE/MAX. She holds a bachelor's degree in journalism from the University of Florida and a master's degree in public relations from Ball State University.