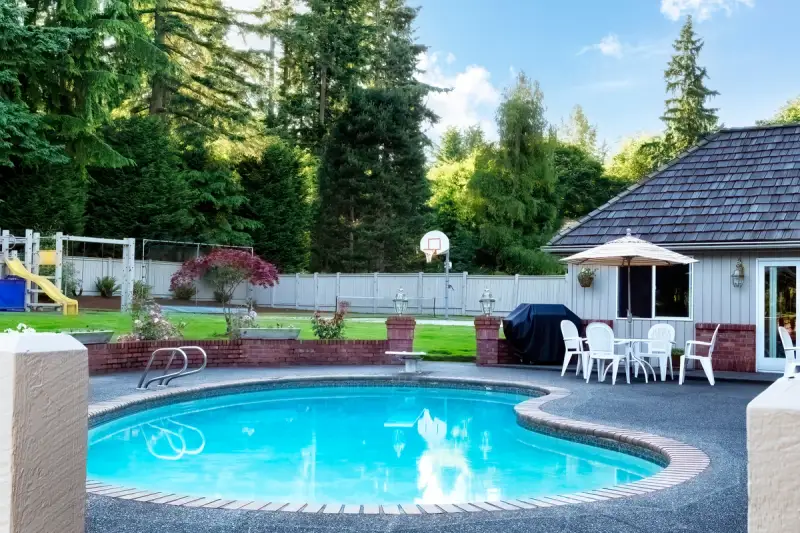
Pools often are the first thing people think about when summer is on the way, and rightly so. What’s better than having your own swimming pool in the backyard during the height of summer? If getting a pool is on your radar, the price tag can vary from $45,000 to over $200,000 for an inground pool. Location, materials, landscaping and safety features like fencing and covers can push costs higher, meaning building the pool of your dreams might require some financial planning before you break ground. In most areas, however, it can be a strong return on investment, adding value to your home.
Fortunately, there are several options for financing a pool. As a homeowner, you can use your home equity a few different ways, each with its own set of advantages and disadvantages. There are also some alternatives if you prefer to keep your equity intact. Let’s dive into the options.
Key Takeways:
- Popular equity-based financing options include a home equity loan, a home equity line of credit and a cash-out refinance.
- Personal loans and in-house pool financing are unsecured and usually come with higher interest rates.
- Local costs such as permitting, electrical work and fence requirements could increase your budget beyond basic pool installation.
5 Strategies To Consider When Financing A Pool
A pool is a big investment, so it pays to do your homework. Here’s a breakdown of the five most common financing options to find the one that works best for you.
1. Home Equity Loan
A home equity loan allows you to use your home’s equity as collateral. You receive the money in one lump sum and make regular monthly payments for a set term. The interest rate is usually fixed and low compared to other types of loan products.
To qualify for a home equity loan, you’ll need to speak with a lender to determine how much equity you currently have in your home. The good news is that if your home has appreciated since you bought it, you may have more equity in your home than you think.
Some lenders allow homeowners to borrow up to 90% of their home’s value, minus the remaining balance on their mortgage.
| Pros: | Cons: |
|---|---|
| Fixed payments: Home equity loans are easy to budget for because the payment remains the same month to month. | Expensive closing costs: You’ll pay upfront closing costs that can range from 3% – 6% of your loan amount. |
| Lower interest rates: Because the loan is secured with a high-value asset, interest rates usually are lower than those for personal loans. | Home is used as collateral: Because your home is used as collateral, your home may be foreclosed if you default on the loan. |
| Easier to qualify for larger amounts: Compared to personal loans, it’s easier to borrow a large amount because you are using your home as collateral. | Higher monthly payments: Financing a pool increases your overall budget each month. |
Compare Home Equity Offers From Verified Lenders:
2. Home Equity Line Of Credit
Also called a HELOC, a home equity line of credit works similar to a credit card with a credit limit based on the equity in your home, but it has a much lower interest rate, which can be fixed or variable. If you take out a HELOC, there is a draw period where you can pull funds as needed and make interest only payments. After the draw period ends, you enter the repayment period – paying back the principal and interest for a set term.
| Pros: | Cons: |
|---|---|
| Borrow money as you need it: Draw money only as you need it. | Variable interest rate: Although some HELOCs offer fixed interest rates, many are variable and are tied to current market rates. Choosing this option means payments could increase over time. |
| Interest-only payments during draw period: While you need to make payments during the draw period on any amount pulled, you don’t need to pay both principal and interest. You need to pay the interest only. | Reduces home equity: With less home equity, you won’t have as much profit when you sell your home. Additionally, you’ll have closing costs and fees that cut into your overall returns. |
| Lower interest rates: Compared to credit cards and personal loans, the interest rates on HELOCs are lower. | Home is used as collateral: If you default on HELOC payments, you may lose your home to foreclosure. |
3. Cash-Out Refinance
A cash-out refinance might be a good option if you have a lot of equity in your home. Here’s how it works: You exchange your current mortgage with a larger one and receive the difference between the two in cash.
Lenders who offer this loan typically require at least 20% equity (a loan-to-value ratio of 80%), a stable income, a good credit score and a low debt-to-income ratio (DTI).
| Pros: | Cons: |
|---|---|
| Potentially lower interest rate than home equity financing: A cash-out refinance may get you a lower interest rate (compared to your current primary mortgage) if the current market rate is lower than what it was when you bought the home. In addition, as a cash-out refinance is designed as a standard mortgage, it also may offer a lower interest rate than a home equity loan. | Longer funding process: A cash-out refinance can take between 30 – 45 days to close, which is longer than personal loans. |
| One payment: Instead of having your mortgage and another loan product, a cash-out refinance makes it so you have only one loan and one payment to make each month. | High closing costs: Refinancing closing costs are typically between 3% – 6% of the loan amount. |
| More loan term flexibility: As a cash-out refinance is structured as your new primary mortgage, you may use this loan to restructure your mortgage to longer or shorter loan terms to fit your repayment goals. You also may be able to choose a variable or fixed-interest loan. | Appraisal required: Your home must be appraised and you need to cover this cost. The appraisal ensures that the loan amount adheres to the LTV requirements of the lender. For example, if the borrower seeks a cash-out refinance totaling $300,000, the home must appraise for $375,000 to adhere to an 80/20 LTV (if that was the lender’s requirement). |
4. Personal Loan
A personal loan is a lump-sum loan, meaning you receive the money all at once. As with a home equity loan, you pay it back in fixed monthly payments. Unlike a home equity loan, though, it is an unsecured loan and often comes with a higher interest rate.
To qualify, you’ll need a good credit score, a stable income and a low DTI.
| Pros: | Cons: |
|---|---|
| Fast funding: Personal loans are often both approved and disbursed very quickly. Sometimes funding comes through in a single day. | May be harder to qualify for: While secured personal loans do exist, many personal loans found online are unsecured. Because of this, you’ll need a good credit score to qualify. Some lenders may accept applications with a score as low as 610, but many require a higher score. |
| No collateral required: Many personal loans do not require collateral, so you don’t have to put any of your assets, such as your house, at risk. | Higher rates: Interest rates on personal loans are typically much higher than those for home equity loans. Interest rates for personal loans may range from around 8% to more than 29%; creditworthiness and other factors may impact the rates borrowers receive. |
| Shorter loan term: Many personal loans are only for five years. Compared to other loan types, you may save money in interest going this route. Use a loan calculator to compare. | Higher monthly payments: You may save money in interest with a shorter loan term, but you’ll have higher monthly payments, which may put it out of your budget. |
5. Pool Retailer Financing
Pool companies often offer customers financing through specified lenders they work with directly. If you’re having trouble finding a personal loan large enough to cover a pool purchase and you don’t want to tap into your home’s equity, retailer financing could be a viable option.
| Pros: | Cons: |
|---|---|
| May be easier to qualify for: Retailers who offer financing through third-party lenders are more likely to lend to you even if you have less-than-ideal credit. Qualification requirements vary, but some programs are designed for borrowers with less-than-perfect credit. | Down payment: Financing your pool’s purchase through a retailer will likely require a down payment. The amount of the down payment varies by retailer. You might have to shop around to see if you can find a no-down-payment promotion plan. |
| Convenient: Choose your pool and loan type at the same place. For some, too many lender options can cause analysis paralysis and stifle movement and keep projects from taking off. | Higher interest rates: You’ll likely pay more interest with retailer financing than you would with a home equity loan. |
| Promotional offers: Shop around at the right time, and you may find a retailer offering some great promotions. | Non-flexible terms: With a home equity loan, you can shop around for better terms with another lender. When you finance through a retailer, your only option is to find another retailer who installs in your area and hope it offers better financing options. |

Discover mortgage options that fit your unique financial needs.
Refinance your mortgage to have more money for what matters.

Use your home’s equity and unlock cash to achieve your goals.
Tips For Financing A Pool
Before you start filling out applications, check out these tips for financing a pool.
- Stick to your budget: There are many variables that can affect the total cost of your pool. When you are purchasing your pool, establish a budget beforehand and stick to it.
- Check permit and additional installation costs: Installing a pool typically requires a local building permit, electrical work and fencing requirements. All of this can add thousands of dollars to your budget.
- Compare different types of financing: Each loan comes with its own set of benefits and drawbacks. Familiarize yourself with each to determine which one is best.
- Save for a down payment: If you opt for retailer financing, you may be required to make a down payment.
- Factor in future maintenance costs: While you may be able to afford the monthly payments if you finance, consider the yearly costs of maintaining a pool. Costs vary with pool type and filtration systems.
Let’s match you up with lenders who can help with your unique financial situation.
FAQ
How long should you finance a pool?
What to do when you can’t afford a pool?
What is the most budget-friendly pool?
What is the most expensive part of building a pool?
See how much you could get.
The Bottom Line: Choose The Best Type Of Financing For Your New Pool
The best type of pool financing depends on your personal situation. If you have substantial equity in your home, ask yourself if you are willing to use it as collateral to secure a home equity loan. If you’re not, a personal loan or retailer financing may be the best route to take.
when you’re ready.


Lauren Ward
Lauren Ward is a writer with over a decade of experience covering financial topics for businesses and publications. Her work has also been featured in major publications such as U.S. News and World Report, CNN, Business Insider, The New York Post and Bankrate. Her expertise includes real estate, mortgages, small business, insurance and more.